

In 2026 and into 2027, the Mechanical, Electrical, and Plumbing (MEP) industry is being reshaped by a number of trends that have emerged over the past few years and are now accelerating. This includes automation and artificial intelligence (AI), sustainability, smart building integration, Building Information Modeling (BIM), and other technological innovations.
Simultaneously, the MEP industry is facing numerous constraints in 2026, including skilled labor shortages, the increasing cost of raw materials, and waning sentiments among consumers and contractors.
With technology evolving quickly and the introduction of new standards and codes, building products manufacturers face a variety of both challenges and opportunities within the construction and remodeling industry. Using custom market research can help industry stakeholders stay on top of emerging trends, enhance product development, and design the best go-to-market strategies.
What are Key Trends and Disruptors in the MEP Industry in 2026 and into 2027?
As you strategize for the future, here are some of the potential disruptors, constraints and trends impacting the MEP industry:
1. Skilled Labor Shortage in Construction
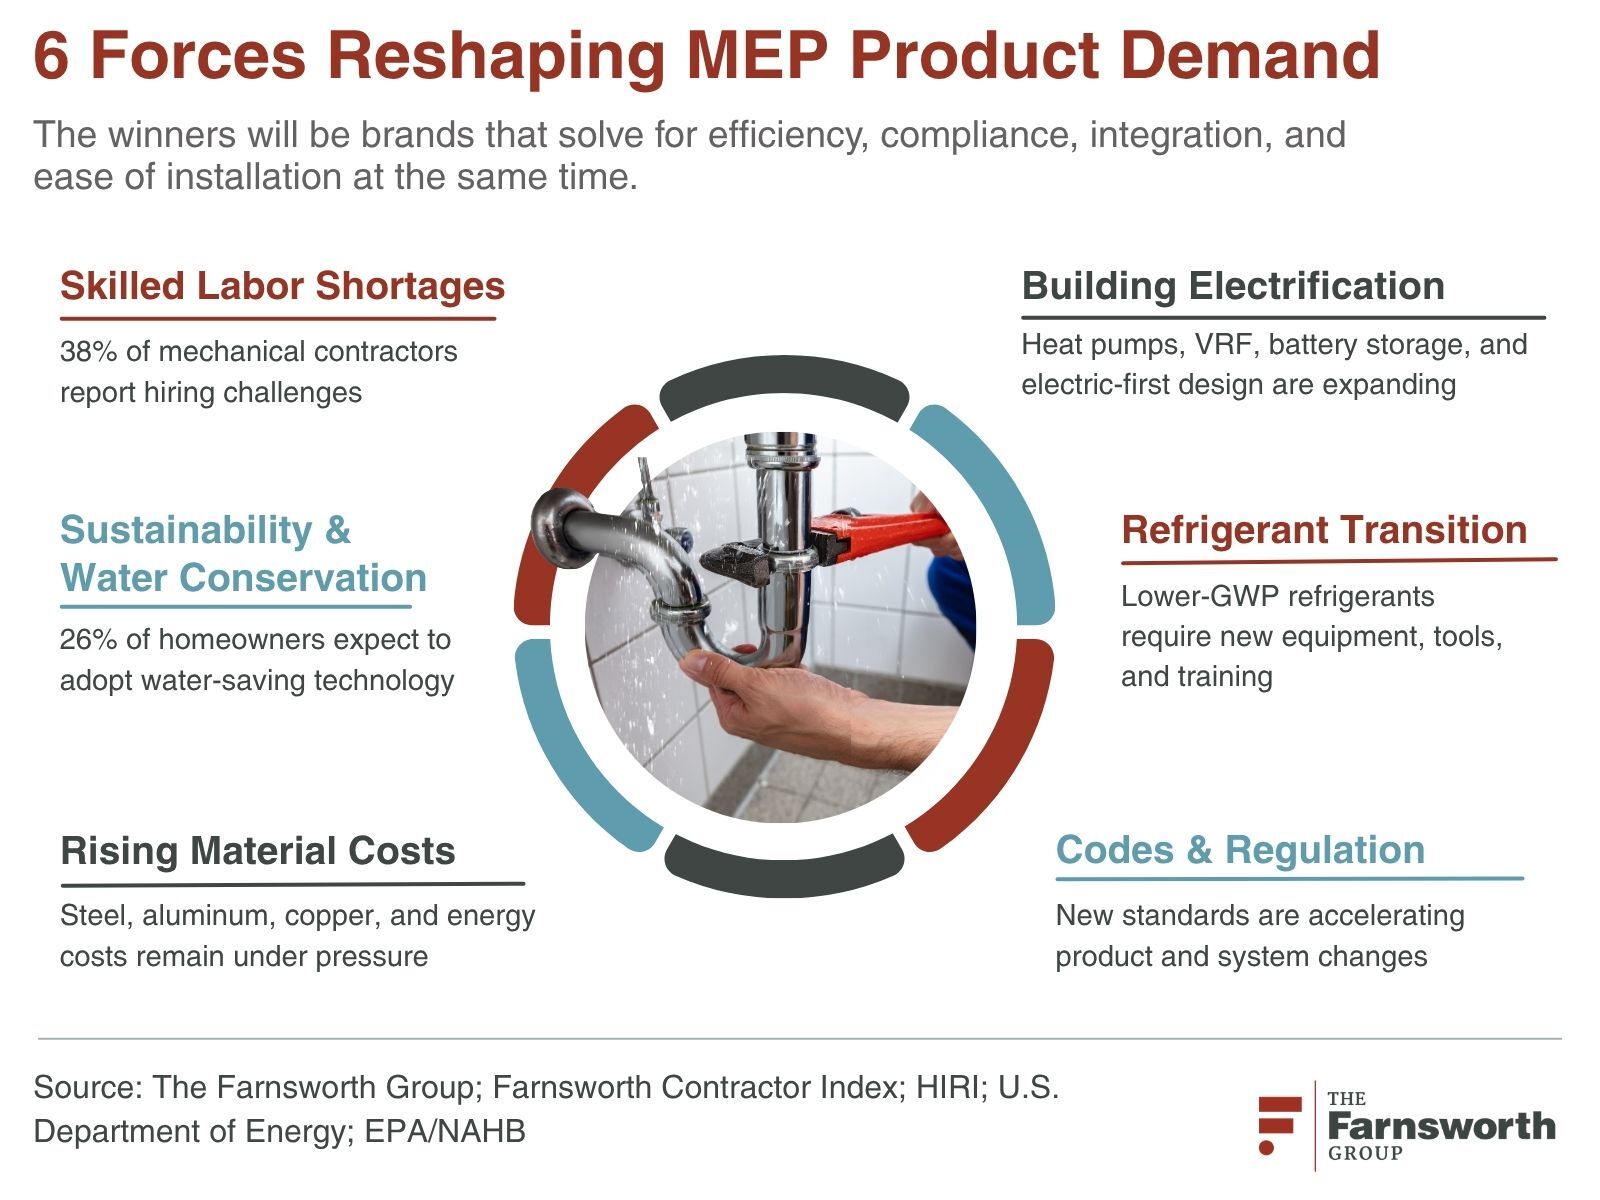
The MEP industry is not immune to the skilled labor shortage that’s currently affecting many businesses, and in fact, this shortage has lasted several years already. Based on findings in the Farnsworth Contractor Index for Q3 2026, about 38% of mechanical contractors are facing challenges hiring skilled labor this quarter, up from 31% in Q2 and up from 29% in the same quarter last year. Assuming they had no challenges with hiring skilled labor, about 34% feel they could increase their revenue by 6% to 10% in the next 12 months and 24% feel they could increase their revenue by 11% to 20%.
As this challenge continues to color the outlook for construction companies, builders and remodelers, and specialty installers in the coming years, these professionals are seeking ways to be more efficient with their workforces and on projects—such as adopting productivity-tracking software—while also employing solutions for employee retention. With twice as many jobs in MEP trades as there are trained professionals to work them, many companies are implementing apprenticeships to appeal to and effectively train new employees.

2. Increasing Demand for Green Plumbing and Sustainability
Worsening water shortages in the western United States, increasing concerns about water quality, and a growing demand for solutions to deal with water conservation are also driving innovation and green plumbing trends. Various technologies, even including AI and automation, are being used to digitize plumbing and help address growing concerns—and they present an opportunity for market growth in the coming years.
According to data from the Home Improvement Research Institute’s (HIRI) Homeowner Trends in Energy Efficiency, Smart Home and Sustainability Study, about 26% of homeowners listed water-saving tech (such as smart irrigation, low-flow fixtures, and shut-off valve devices) as one of the technologies they are most likely to adopt in the next five years. Middle-income families, in particular, prioritize social/environmental consciousness and are more likely to invest in water-saving technologies.
There is an opportunity for development and improvement in the category, given the technical nature of these types of products, including smart water-leak detectors and humidity monitoring devices.
3. Expanding AI, Automation, and Augmented Reality
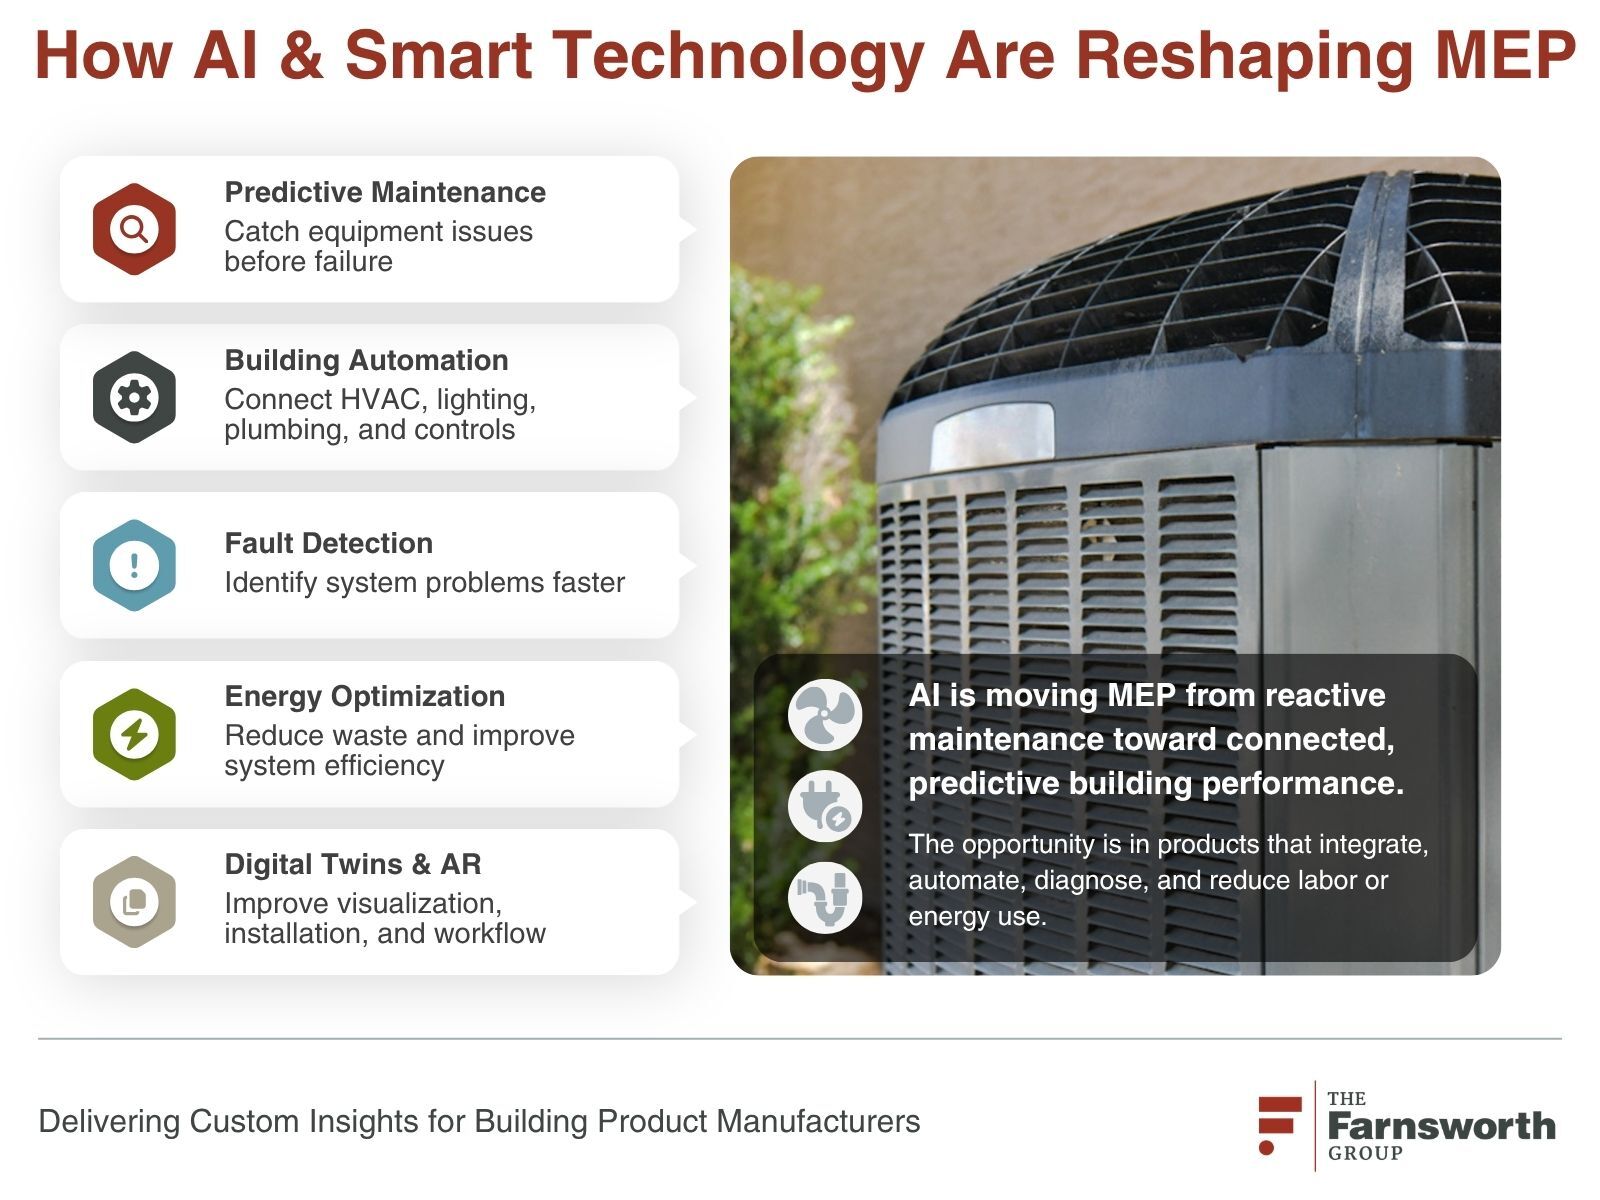
AI and automation extend beyond the plumbing sector. These technologies are also at work helping with better building decisions, automating the installation process, connecting home systems, increasing IAQ in residential and commercial buildings, and saving fuel. Augmented reality (AR) is also on the rise, to the benefit of both MEP contractors and their customers.
Some of the ways AI and AR have been applied in the MEP industry include:
- Predictive maintenance
- Building automation
- Fault detection
- Energy optimization
We’re also seeing a higher use of digital twins in construction; they are used to mirror real-time site program, monitor system performance, and validate installation workflows, which can optimize execution and help with early detection of deviations. Additionally, MEP companies can make time-consuming tasks more efficient using fabrication software and automate cutting tools. By merging digital and real worlds, AR enables them to better visualize different stages of a construction project and work with more efficiency and clarity.
Smart Technologies for MEP Systems
Smart technologies are also being embedded directly into MEP systems in both residential and commercial buildings. These include items like:
- Smart thermostats
- Variable-speed HVAC
- Load-monitoring panels
- EV charger integration
- Leak detection sensors
- Smart water heaters
These products are being incorporated to optimize comfort, reduce waste, and enable remote monitoring for property owners.
4. Eco-Friendly HVAC Trends
The plumbing sector isn’t the only segment working to bring to market alternative options. Demand for energy efficiency and the push for better indoor air quality (IAQ) is also influencing the HVAC industry, leading to new building initiatives and renovation projects. The goal here will be to develop solutions and tools that reduce energy usage while simultaneously promoting health and safety.
With the influx of natural gas bans across the country, companies will be seeking eco-friendly alternatives for heating, such as hydrogen fuel. The U.S. Department of Energy’s Alternative Fuels Data Center can be a useful resource moving forward as MEP engineers design for lower energy consumption, reduced carbon emissions, and compliance with tightening regulations.
5. Rising Costs for Raw Materials
The price of raw materials has continued to rise in 2026, affecting multiple sectors. This is a result of global market volatility, U.S. trade policy, the ongoing war with Iran, and supply chain pressures. These are affecting individuals, as well as companies, and influencing lifestyle changes that could create disruption for the MEP industry.
For example, in mid-2025, the U.S. put a hefty tariff on imported metals, up to 50% for products made entirely or almost entirely of aluminum, steel and copper. There have been numerous changes to the policy over the past year and a half, and how they have been applied to different countries of origin, all of which have created uncertainty and volatility in the market. In response, we expect contractors and construction companies will be more likely to shop around for materials to reduce project costs while retaining top labor.
Another cause behind the inflated price of raw materials is the rising rate of energy. When that’s alleviated, we are likely to see those prices go down. But currently, all forms of energy—from oil and natural gas to electricity and liquefied petroleum (LP) gas—are still more expensive than they used to be. While it’s hard to predict what will happen over the next five years with the geopolitical landscape, it’s clear that tensions globally are creating international ripple-effects are creating market uncertainty and causing disruption in the energy market, in particular.
As a result, there’s a pressing need for industrial manufacturers to develop and distribute equipment and individual components that can save energy, such as higher-efficiency systems and ECM circulating pumps.
6. Changes to Building Electrification
Electrification is forcing MEP engineers to rethink system sizing, equipment selection, and integration strategies. The result is a push toward all-electric, high-efficiency systems that align with tighter building codes and building decarbonization goals. The demand is for smarter, more resilient, and renewable-integrated buildings that also deliver long-term value.
For example, gas-fired boilers, chillers, and furnaces are being replaced by electric heat pumps, VRF systems, and all-electric boilers/chillers. These technologies offer higher efficiency, lower emissions, and better integration with renewable energy. MEP teams now design HVAC systems with an “electric-first” mindset, ensuring compatibility with future grid conditions and renewable generation.
Additionally, buildings are increasingly incorporating on-site solar, battery storage, and microgrids to reduce grid dependency. MEP planning now accounts for multi-source energy flows, load balancing, and backup autonomy, ensuring stable power quality.
Electrified systems are being paired with building-wide smart systems that control HVAC, lighting, and plumbing, enabling automation, occupancy-based optimization, and predictive maintenance.
While this process is most cost-effective in new construction, where like-to-like equipment costs and the elimination of gas distribution infrastructure yield savings. Retrofitting existing mixed-fuel systems is more expensive and complex.
7. Impact of the Refrigerant Transition
Driven by EPA regulations under the American Innovation and Manufacturing (AIM) Act, the HVAC industry is transitioning from high-GWP refrigerants, such as R-410A, to low-GWP alternatives, such as R-454B and R-32. The latter are both A2L-class refrigerants that are mildly flammable but non-toxic.
HVAC teams must update safety protocols, tools, and technician certifications to handle mildly flammable refrigerants safely. The National Association of Home Builders also points out that equipment design will likely need modifications to comply with A2L standards, and proper leak detection and recordkeeping are essential for regulatory compliance.
The industry is investing heavily in research, training, and equipment redesign to ensure energy efficiency and safety during this transition. Although the compliance timeline varies for different products and players, contractors and building owners should plan ahead for this transition to avoid supply bottlenecks and ensure smooth installation of compliant systems.
8. Changes in Regulatory Requirements and Building Codes
Manufacturers and engineers in the MEP industry also have to comply with a nuanced set of model codes, trade-specific standards, and local regulations to ensure safety, efficiency, and sustainability in design, construction, and operation. This includes the International Building Code; International Mechanical Code (IMC); International Plumbing Code (IPC); International Fire Code (IFC); and National Electrical Code (NEC). Since these codes are regularly updated, it’s important to stay on top of relevant changes.
For example, the NEC is being updated in 2026 to address contemporary technologies, such as Electric Self-Propelled Vehicle Power Transfer Systems (ESVSEs) and other emerging electrical applications, reflecting the evolving landscape of electrical systems. Additionally, several new articles have been introduced, particularly focusing on high-voltage systems and limited-energy systems.
There has also been an increase in state and local bans on natural gas, which will shift focus to the development of highly efficient heat pumps. One example of this is the California Air Resources Board (CARB) announcing a comprehensive plan to ban the sale of natural gas heaters, furnaces and water heaters by 2030. As regulations and requirements such as these emerge over the next five years, it will force a shift for manufacturers, distributors, contractors, professional installers, DIYers and distributors.
These changes to the building codes create a trickle-down effect, especially among Pro customers, who are often facing higher product and project costs with the need to utilize compliant materials. These changes may also change how they complete the work and what kinds of subcontractors and trade specialists will be best suited for the job. Where Pros purchase materials is less likely to change as long as their preferred supplier has the compliant materials they need, based on our findings in the 2026 Building Products Customer Guide.
Planning for Future MEP Disruptors with Market Research
While you can’t control what regulations, innovations, occurrences and market challenges might shake the MEP industry, you can be prepared to deal with them by fostering resiliency and having the right data to work with.
Some of the questions that building products brands should be asking about the future of the MEP industry include:
- How will electrification change HVAC demand?
- What impact will lower-GWP refrigerants have on product development?
- Which technologies are reshaping commercial building design?
- How are contractor labor shortages influencing product selection?
- How is AI changing building operations and maintenance?
- What sustainability trends are influencing purchasing decisions?
- Which market disruptions are likely to have the greatest long-term impact?
Conducting customized market research with the help of our team at the Farnsworth Group enables you to gather meaningful market insights to inform your business strategies and prepare you for what lies ahead.
Frequently Asked Questions
How are skilled labor shortages affecting the MEP industry?
Mechanical, Engineering, and Plumbing (MEP) contractors have experienced an extended shortage of skilled labor over the past couple of years. Based on findings in the Farnsworth Contractor Index for Q3 2026, this has been a growing challenge for contractors in 2026. Additionally, it is a challenge that contractors feel is at least partially affecting their ability to grow their business and increase revenue. As this challenge continues to color the outlook for construction companies, builders and remodelers, and specialty installers in the coming years, these professionals are seeking ways to be more efficient with their workforces and on projects—such as adopting productivity-tracking software—while also employing solutions for employee retention.
What sustainability trends are influencing purchasing decisions for MEP products?
There are several sustainability trends influencing decision-making around the purchase of Mechanical, Engineering, and Plumbing (MEP) products. These include energy efficiency, water conservation, decarbonization goals, circular material use, and smart building integration, all of which are influenced by regulatory compliance and sustainability certifications. Various technologies, even including AI and automation, are being used to digitize plumbing and help address growing concerns—and they present an opportunity for market growth in the coming years.
What is the impact of regulatory requirements and building codes on the MEP market?
Manufacturers and engineers in the Mechanical, Engineering, and Plumbing (MEP) industry have to comply with a nuanced set of model codes, trade-specific standards, and local regulations to ensure safety, efficiency, and sustainability in design, construction, and operation. Since codes are regularly updated, it’s important to stay on top of relevant changes, which create a trickle-down effect. This is especially true among Pro customers, who are often facing higher product and project costs with the need to utilize compliant materials. These changes may also change how they complete the work and what kinds of subcontractors and trade specialists will be best suited for the job. Where Pros purchase materials is less likely to change as long as their preferred supplier has the compliant materials they need, based on data from The Farnsworth Group's 2026 Building Products Customer Guide.

Written By
Karen Barnes
Through her expertise in brand consulting, market research design, and advanced analytics, Karen has been helping answer critical business questions for the past 15 years. She has had the privilege of working with many of the top global insights organizations and applying best practices across a myriad of clients in CPG, technology, finance, healthcare, and of course home improvement, including developers, building products manufacturers, and retailers.
An Iowa native, Karen was upgrading from riding mowers to full combines at the annual John Deere employee fair by age 7. Now in Denver, she fills her off hours hiking the Rocky Mountains, uncovering the best local food & drink spots, and traveling as much of the world as humanly possible with her fiancé, Adam.
Written By
Eric Voyer
Eric brings nearly 30 years of experience in market research, business development, and strategic consulting within the home improvement, building products, and outdoor industries. He spent decades in syndicated research for consumer durables, where he helped leading brands turn complex data into actionable insights that drive growth. Eric's expertise spans both quantitative and qualitative methodologies. At The Farnsworth Group, Eric focuses on client engagement, project design, and strategic storytelling to ensure insights lead to clear, confident decisions.
Originally from Orlando and now based in Louisville, KY, Eric studied Business at Transylvania University, where he also competed as a collegiate goalkeeper. Outside of work, Eric still enjoys playing soccer, loves to Ski and Scuba and has a new passion for playing ice hockey.